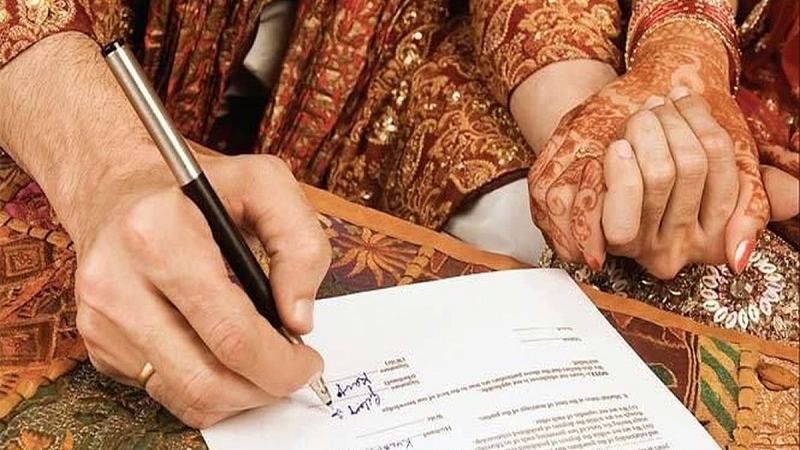
Abdul Kader: In a recent development, Dhaka South City Corporation (DSCC) has introduced a tax policy for marriage registration, presenting a complex set of conditions. This policy, applicable only in Dhaka South and North City Corporation, aims to regulate marriage taxes based on certain criteria outlined in Section 50 of the 'City Tax Rules' and Section 10(4) of the 'City Corporation Standard Tax Schedule, 2016'.
Under this policy, taxes vary depending on the circumstances of the marriage. For instance, in the case of a second marriage with the first wife's permission, the tax is set at 5,000 taka, whereas a fourth marriage incurs a tax of 50,000 taka. Notably, exceptions are made for marriages involving mentally unstable or barren wives, with a fixed tax of 200 taka for those cases.
However, the challenge lies in the implementation of this policy, given that the marriage registration system in Bangladesh is currently paper-based and lacks digitalization. DSCC faces concerns regarding how to effectively enforce these taxes, particularly in cases of individuals committing multiple marriages to evade taxes.
The 'Muslim Marriage and Divorce (Registration) Act, 1974,' mandates the registration of all Muslim marriages by the Nikah Registrar. Violation of this provision is a statutory offense punishable by imprisonment or a fine. Similarly, non-Muslim citizens' marriages are regulated under the Special Marriage Act, 1872, with Section 11 requiring registration in the presence of the registrar and witnesses.
The DSCC's new policy, purportedly applying universally to all religions within its jurisdiction, contradicts the Special Marriage Act, which deems remarriage during a spouse's lifetime an offense. This incongruity raises questions about the feasibility and legality of the proposed tax policy.
Moreover, the existing paper-based marriage registration process lacks centralization, making it challenging to monitor and rectify anomalies. With marriage registrars not being civil servants, accountability and motivation for registration are limited, resulting in a significant number of unregistered marriages in Bangladesh.
In conclusion, while DSCC aims to enhance revenue through its new tax policy, the existing hurdles in the marriage registration system call for comprehensive reforms and digitalization to ensure effective implementation and adherence to legal frameworks.